How to Build a Simple Household Budget That Actually Works
By The My Simple Living Tips Team ·
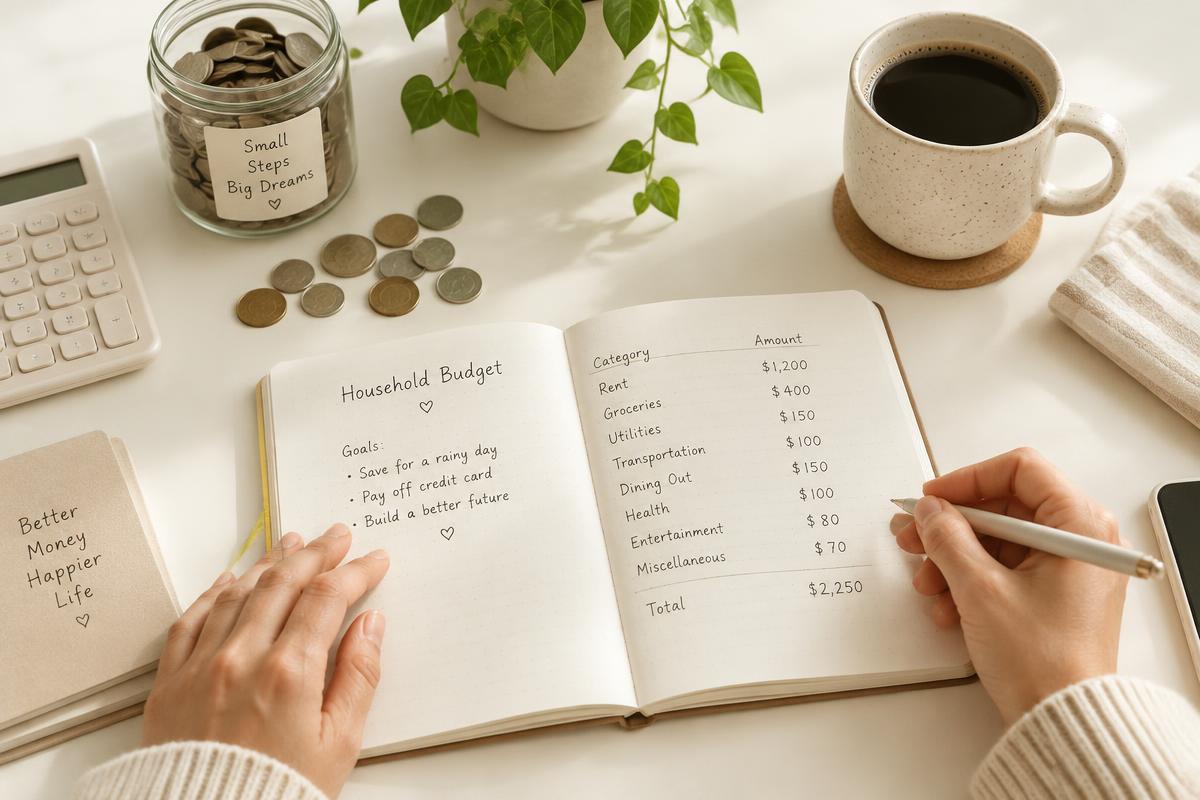
A budget is simply a plan for your money. It does not have to be complicated or restrictive. The aim is to understand where money goes each month so you can make choices that match your priorities. This article offers general information only and is not financial advice.
Step 1: Know your monthly income
Start with the amount that actually arrives in your account after taxes and deductions. If your income varies, use a conservative estimate based on a lower-earning month.
Step 2: List your regular costs
- Fixed costs: rent or mortgage, insurance, phone and internet.
- Variable essentials: groceries, utilities, transport.
- Flexible spending: eating out, hobbies, subscriptions, gifts.
- Irregular costs: car repairs, annual fees, holidays. Divide these by twelve.
Step 3: Track for one month
Before making big changes, simply observe. Write down or use an app to record everything you spend for a month. Most people find at least one surprise, often small purchases or forgotten subscriptions.
A budget is not about saying no to everything. It is about saying yes to the things that matter most to you.
Step 4: Choose a simple framework
A popular starting point is to divide take-home pay into needs, wants and savings. The exact percentages depend on your situation and local living costs, so treat any rule of thumb as a guide rather than a requirement.
Step 5: Look for gentle adjustments
- Review subscriptions and cancel ones you rarely use.
- Plan meals for the week to reduce food waste.
- Compare insurance and phone plans once a year.
- Set up a small automatic transfer to savings on payday.
Step 6: Review regularly
Set aside fifteen minutes each month to compare your plan with what actually happened. Adjust categories as life changes. A budget is a living document, not a test you pass or fail.
Keep expectations realistic
Everyone's finances are different, and results vary. If you are dealing with debt or complex financial decisions, a qualified financial adviser or a free non-profit credit counseling service can provide guidance tailored to your situation.
It can also help to involve everyone in the household. A short monthly chat about upcoming costs and shared goals keeps surprises to a minimum and turns budgeting into a team effort rather than one person's job.